Winter Park Condo Association Insurance
9:00am - 5:00pm Mon-Fri
We'll Reply in 15min*
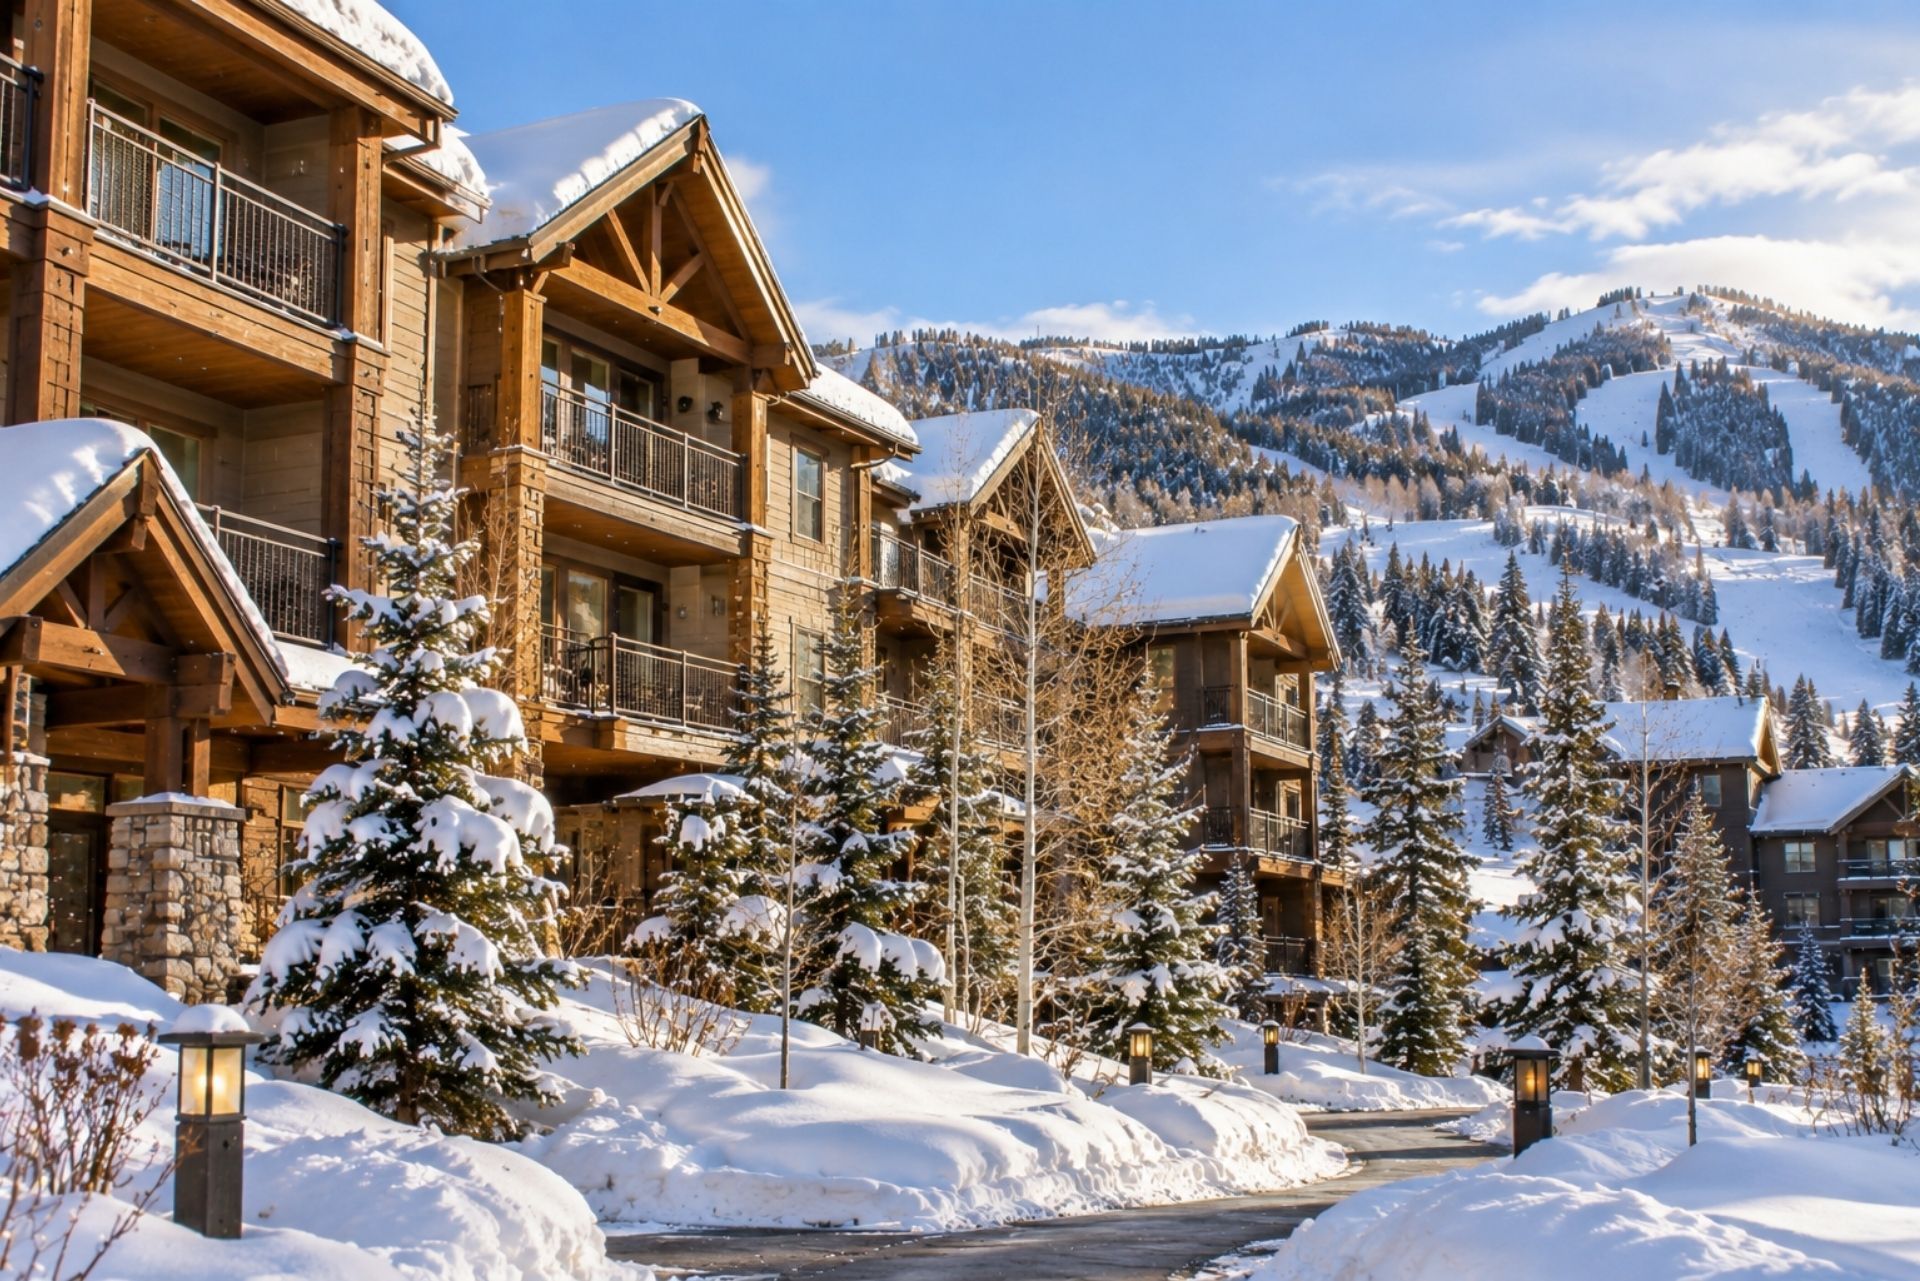
Winter Park sits at roughly 9,000 feet, surrounded by national forest and exposed to conditions that most condo associations in lower-altitude markets never think about. Wildfire smoke drifts through every summer. Snow accumulates on roofs for months. Spring runoff finds its way into basements and parking structures. If you serve on a condo association board here, your insurance program isn't just a line item: it's the single biggest financial decision you'll make each year.
Colorado property insurance premiums have doubled since 2020, with a 55% increase since 2023 alone. That cost pressure makes it tempting to cut corners, but a poorly structured master policy can leave individual owners and the association itself exposed to six-figure gaps. Understanding how condo association insurance works in Winter Park, from wildfire and snow load risks to building valuation, water damage, liability, and claims, is no longer optional knowledge for board members. It's a fiduciary responsibility.
The stakes are real. A single under-insured water damage claim or a wildfire that triggers an ordinance-or-law upgrade can bankrupt a reserve fund overnight. This guide walks through the specific coverage structures, Colorado-specific risks, and practical decisions that Winter Park associations face right now in 2026.
Understanding Master Policies in Winter Park
Every condo association carries a master policy, but the type of master policy dictates what the association covers versus what falls on individual unit owners. Getting this wrong is one of the most common mistakes we see boards make. A unit owner assumes the association's policy covers interior drywall after a pipe burst, only to discover the master policy stops at the studs.
Colorado's Common Interest Ownership Act (CIOOA) requires associations to insure common elements, but the governing documents determine how far that coverage extends into individual units. Your CC&Rs and bylaws should spell this out, yet many Winter Park associations operate with declarations drafted decades ago that don't reflect current construction costs or risk profiles.
Bare Walls-In vs. All-In Coverage
A bare walls-in policy covers only the building's structural shell: exterior walls, roof, foundation, and common area systems like elevators and hallways. Everything inside the unit, including flooring, cabinets, fixtures, and interior walls, is the owner's responsibility. This is the most common structure in Colorado mountain communities.
An all-in policy, by contrast, covers the unit interior as originally built. If a pipe bursts and destroys the kitchen, the association's master policy responds for the original cabinets and countertops. Owner upgrades, like granite replacing laminate, still fall on the owner's HO-6 policy. The all-in approach simplifies claims but raises the association's premiums and insurable value significantly.
Common Area Responsibilities
Common areas extend beyond lobbies and pools. Think about parking garages, ski storage rooms, fitness centers, hot tubs, walkways, and retaining walls. Each of these creates both property and liability exposure. A cracked retaining wall that shifts during spring thaw can damage a neighboring property, and that's a liability claim against the association.
Boards should inventory every common element annually. Winter Park's freeze-thaw cycles accelerate wear on concrete, decking, and exterior stairs. If a common area element fails and causes injury or property damage, the association's policy needs to respond, but only if the element was properly scheduled and the coverage limit reflects current
replacement cost.
By: John Jacquat
Founder & President
Critical Coverage Types for Florida Associations
Colorado mountain associations need a layered insurance program. No single policy covers everything, and the gaps between policies are where the real financial danger lives.
Property and Windstorm Protection
Your property policy is the backbone. It should cover the building at full replacement cost, not actual cash value (ACV). ACV deducts depreciation, meaning a 20-year-old roof that costs $400,000 to replace might only pay out $180,000 under an ACV policy. For a mountain building exposed to heavy snow, high winds, and hail, that gap can be devastating.
Windstorm and hail coverage in Colorado mountain towns often carries a separate percentage deductible, typically 1% to 5% of the building's insured value. On a $10 million building, a 3% wind/hail deductible means $300,000 out of the association's pocket before the carrier pays a dime. Board members should know their deductible structure cold.
General Liability and Umbrella Policies
General liability protects the association when someone is injured on the property or when the association's negligence damages someone else's property. Slip-and-fall claims on icy walkways are the bread and butter of Winter Park liability exposure. Under the Colorado Common Interest Ownership Act (CCIOA), the law requires liability insurance in an amount "specified by the association documents" or "deemed sufficient in the judgment of the executive board" (https://dre.colorado.gov/sites/dre/files/documents/2026 Colorado Common Interest Ownership Act (38-33.3-101 et seq).pdf).
The umbrella policy kicks in when the underlying general liability limit is exhausted. It also typically extends over the association's auto liability (if the association owns vehicles for maintenance) and employer's liability.
Directors and Officers (D&O) Liability
Board members make decisions about contracts, assessments, rule enforcement, and vendor selection. Any of those decisions can trigger a lawsuit from a disgruntled owner. D&O liability insurance covers the legal defense costs and potential settlements arising from alleged wrongful acts in board governance.
Without D&O coverage, individual board members could face personal financial exposure. That's a fast way to lose every volunteer willing to serve. A typical D&O policy for a Winter Park association is a critical expense that varies depending on the number of units and claims history, and it's worth every dollar.
Comparing Master Policy Structures
Choosing the right master policy structure affects every owner in the building. Here's how the three main approaches compare side by side.
Comparison: Bare Walls vs. Single Entity vs. All-In
| Feature | Bare Walls-In | Single Entity | All-In |
|---|---|---|---|
| Structural shell | Covered | Covered | Covered |
| Original interior finishes | Not covered | Covered | Covered |
| Owner upgrades | Not covered | Not covered | Covered |
| Association premium | Lowest | Moderate | Highest |
| Owner HO-6 burden | Highest | Moderate | Lowest |
| Claims complexity | Higher (disputes over boundaries) | Moderate | Lower |
| Common in Winter Park? | Yes | Sometimes | Rare |
Most Winter Park associations use bare walls-in because it keeps the master policy premium lower. The tradeoff is that owners need robust HO-6 policies. Boards should communicate clearly, ideally in writing each year, what the master policy covers so owners don't assume they're protected when they're not.
Single entity coverage is a middle ground that works well for associations where units were delivered with similar finishes. It reduces disputes during claims because the line between "association responsibility" and "owner responsibility" is clearer.
Addressing Colorado-Specific Risks
Winter Park's geography and altitude create insurance challenges you won't find in Denver or Colorado Springs. Two risks stand out above the rest.
Flood Insurance and Elevation Requirements
Standard property policies exclude flood damage. Period. If snowmelt or a flash storm sends water into ground-level units or a parking garage, the master policy won't pay unless the association carries a separate flood policy through the National Flood Insurance Program (NFIP) or a private flood carrier.
Many Winter Park buildings sit near the Fraser River or smaller drainages. Even if your building isn't in a FEMA-designated flood zone, consider the actual water risk. Private flood policies can sometimes offer better terms than NFIP for mountain properties because the risk profile differs from coastal flooding. Elevation certificates for each building help determine accurate premiums and can sometimes reduce costs.
Ordinance or Law Coverage for Older Buildings
Here's a gap that catches associations off guard. If a building constructed in the 1970s or 1980s suffers major damage, the local building code may require upgrades during reconstruction: improved insulation, updated electrical, ADA compliance, or higher snow load capacity. Standard property policies pay to restore the building to its pre-loss condition, not to code.
Ordinance or law coverage fills that gap. It typically adds 10% to 25% to the property premium but can prevent a six-figure special assessment. In Winter Park, where structural snow load requirements range from 70 to over 300 pounds per square foot depending on elevation, a rebuild triggered by a partial collapse could require expensive structural reinforcement that the base policy won't touch.
Colorado's new legislative efforts are also changing the picture. Starting July 1, 2026, insurers must provide associations with a plain-language explanation of their wildfire risk score and disclose the catastrophe models used in pricing. That transparency gives boards real data to challenge inflated premiums or invest in mitigation that actually moves the needle.
Associations should also know about Senate Bill 26-155, which created the Strengthen Colorado Homes Enterprise to
provide grants for retrofitting roofs against hail and wildfire embers. The program will be funded by a 0.5% fee on multi-peril insurance premiums starting in 2027, with 85% of revenue going directly to homeowner and HOA grants. If your association is considering roof replacement or fire-resistant siding, timing the project to coincide with grant availability could save tens of thousands.
Common Questions About Condo Insurance
FAQ: Cost, Claims, and Local Requirements
How much does a master policy cost for a Winter Park condo association? It varies widely based on building age, construction type, number of units, and claims history. Colorado property insurance premiums have doubled since 2020, with a 55% increase since 2023 alone (https://salliesimmons.com/blog/insurance-shock-in-denver-how-rising-costs-are-impacting-condos-hoas-and-homeowners). Older buildings or those with prior water damage claims pay more.
Who files the claim: the association or the individual owner? If the damage involves common elements or falls within the master policy's coverage scope, the association files the claim. If the damage is limited to an owner's unit interior and falls under their HO-6 policy, the owner files. Disputes arise when both policies could arguably respond, which is why clear CC&R language matters.
Does the association need separate wildfire coverage? Wildfire is typically covered under the standard property policy in Colorado, but check for exclusions or sub-limits. Some carriers have introduced wildfire-specific deductibles for mountain properties. Under HB25-1182, insurers must now account for community-level mitigation like defensible space when scoring risk, so investing in mitigation can directly reduce your premium.
What's the biggest coverage gap you see in mountain associations? Water damage from ice dams and frozen pipes. Many associations don't carry enough coverage, or they have high water damage deductibles that make smaller claims impractical to file. Preventive maintenance, like heat tape on roofs and pipe insulation, reduces both claims frequency and premium costs.
Are special assessments covered by insurance?
Not directly. If a covered loss exceeds the policy limit, the association may need to levy a special assessment to cover the shortfall. Loss assessment coverage on individual HO-6 policies can help owners pay their share, but the association itself absorbs the gap between the claim payout and the actual repair cost.
Protecting Your Association's Future
Condo association insurance in Winter Park demands more attention than most boards give it. The combination of wildfire exposure, heavy snow loads, aging building stock, water intrusion risks, and rising premiums creates a situation where last year's policy might not be adequate this year.
Start with an honest building valuation. Get an appraisal every three to five years, not a guess based on what you paid. Review your master policy structure against your CC&Rs to make sure they align. Invest in mitigation, whether that's defensible space clearing, roof retrofits, or pipe insulation, because it reduces both your risk and your premium.
Colorado Insurance Commissioner Michael Conway has said the market alone won't solve affordability, and that innovation is required. Your board can be part of that innovation by actively managing risk instead of passively renewing the same policy each year. Talk to a broker who specializes in mountain community associations, compare at least three quotes, and don't accept a renewal without understanding exactly what changed and why.
ABOUT THE AUTHOR:
John Jacquat
As President of Pure Risk Advisors, I’m dedicated to helping clients protect what matters most through clear, personalized insurance solutions. Since 2009, my focus has been delivering trusted coverage and guidance for individuals and businesses across Colorado and beyond.
The Pure Risk Process
Process of Working With A Business Insurance Agent in Colorado
Risk Analysis & Tailoring
Embark on a meticulous exploration of your business's unique vulnerabilities and aspirations. Pure Risk Advisors goes beyond mere coverage, ensuring you're equipped with solutions finely tuned to Colorado’s distinct business landscape.
Strategic Business Consultation
Dive deep into a strategic session with our seasoned specialists. By delving into your business model, aspirations, and challenges, we align our insurance recommendations not just to protect but to propel your business forward, keeping in mind Colorado’s intricate regulatory environment.
Swift Policy Integration
Upon discerning the optimal protection strategy, we streamline the activation process. Partnering with Pure Risk Advisors means more than just business insurance – it's about securing your enterprise's future with unmatched diligence and expertise in Colorado.
Pure Risk Advisors Team
Meet Our Colorado Professional Team Members
Meet the heart and soul of Pure Risk Advisors: our exceptional team. Each individual has been meticulously selected not just for their deep-rooted industry knowledge, but for their passion and commitment to genuinely serve our clients.
We pride ourselves on forging more than just business transactions; we build relationships. Our team doesn't see you as just another policy number. Instead, they view every interaction as a partnership, crafting solutions that resonate with your unique needs.
Dive in, get to know us, and discover firsthand why our team makes all the difference.
Client Testimonials
Amazing Feedback About Pure Risk Advisors

In today’s insurance marketplace, innovation and originality are important - but unless they’re accompanied by integrity and personalized service, they do little to accomplish a club owner’s goals. ACE National is proud to recognize John Jacquat and his company, Pure Risk Solutions, as one of our top-ranked premier industry providers. John has consistently mastered achievement in leadership, creating the best product for a client’s needs and following through on his word. I can recommend Mr. Jacquat without reserve if you’re in the market for club insurance.
Angelina Spencer
Executive Director of Ace National
Business Insurance Coverage in Colorado
Commercial Insurance Options
Business Owner's Policy
Coverage for property damage, liability, and business interruption combined.
General Liability Insurance
Protects against business liabilities like bodily injury and property damage.
Workers' Comp. Insurance
Covers employee injury costs, ensuring business and worker protection.
Professional Liability Insurance
Guard against professional mistakes, negligence, or services rendered failures.
Commercial Property Insurance
Broad protection against business-related injuries or property damage claims.
Commercial Auto Insurance
Coverage for business vehicles against damage, injury, or liability.
We've been serving Colorado Business Since 2009
Industries Served
Latest News & Blog
Read Our Latest Articles