Aspen Luxury Condo Insurance
9:00am - 5:00pm Mon-Fri
We'll Reply in 15min*
Aspen's luxury condo market sits at an unusual intersection of extreme property values and serious environmental exposure. A single unit in a high-end building can carry finishes, fixtures, and structural materials worth millions, yet the surrounding terrain presents wildfire risk that most urban condo owners never consider. For association boards and individual owners, getting insurance right isn't optional: it's the difference between financial recovery and catastrophic loss.
Condo association insurance in Aspen must account for luxury building valuations, wildfire threats, water damage from snowmelt and plumbing failures, liability from short-term rentals, and deductibles that can surprise even experienced board members. The challenge is that standard policies designed for typical metro-area condos don't reflect the realities of insuring property at 8,000 feet in Pitkin County. Carriers willing to write these policies are fewer than you'd expect, and the ones that remain are pricing risk aggressively.
This piece breaks down what Aspen condo associations and
unit owners need to understand about coverage gaps, wildfire mitigation requirements, liability exposure, and the market forces shaping premiums in 2026. Whether you're on a condo board or own a unit you rent seasonally, the stakes are high enough to warrant serious attention.
The Unique Risk Landscape of Aspen Luxury Condos
Aspen's condo buildings aren't typical multi-family structures. Many feature custom stone, imported hardwoods, commercial-grade kitchen installations, and radiant heating systems embedded in floors that cost more per square foot than entire homes in other markets. These details matter because they directly drive the cost of rebuilding after a loss, and most associations underestimate just how much.
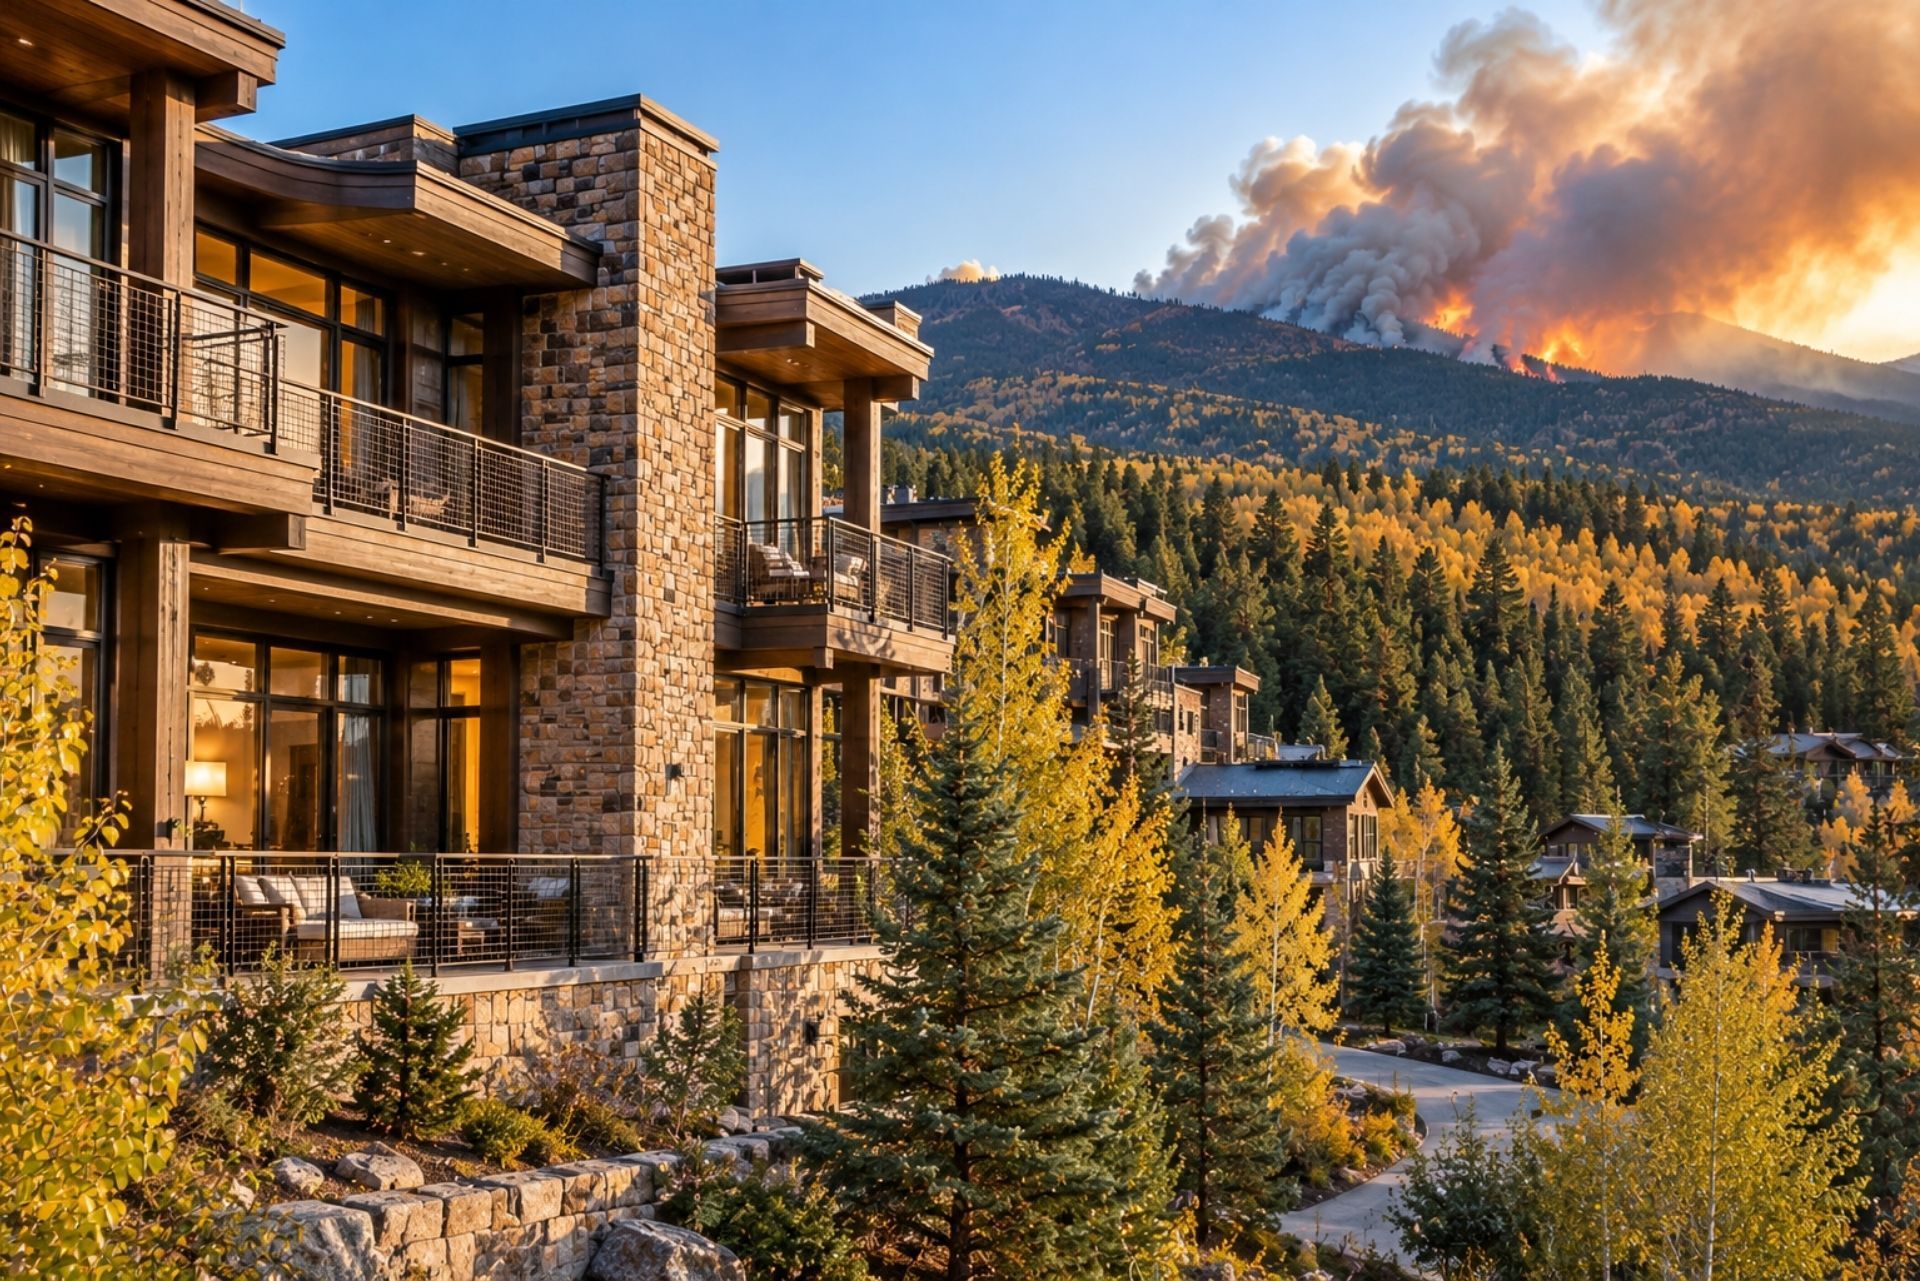
The mountain setting compounds things. Freeze-thaw cycles stress plumbing systems, heavy snow loads test roofing, and the wildland-urban interface creates fire exposure that standard risk models weren't built to handle. Your association's master policy needs to reflect all of this, or you're carrying risk you don't realize.
High Replacement Costs and Specialized Materials
Replacement cost valuations for Aspen luxury condos frequently diverge from market value in ways that confuse boards. A unit selling for $4 million might cost $5.5 million to rebuild because of the labor market in the Roaring Fork Valley, material lead times for custom finishes, and code-upgrade requirements triggered by a total loss.
Associations should commission independent appraisals every two to three years rather than relying on carrier-provided inflation adjustments. Those automatic escalators often use national construction cost indices that don't capture Aspen's reality. If your building's declared value is too low, you'll face coinsurance penalties at claim time, meaning the carrier pays only a proportional share of the loss.
The Impact of High-Altitude Geography on Claims
Water damage is the most frequent claim type for Aspen condos, not fire. Ice dams form when heat escapes through poorly insulated roof sections, melting snow that refreezes at the eaves. The resulting water intrusion can damage multiple units in a single event. Pipe bursts during cold snaps are another constant threat, particularly in buildings where plumbing runs through exterior walls.
Hail at altitude hits harder than at sea level. Roofing materials rated for Front Range conditions may not hold up at 7,900 feet, and carriers know it. Your association's policy should specify agreed-upon replacement with materials rated for your actual elevation and climate conditions.
By: John Jacquat
Founder & President
Mitigating Wildfire Risks in Pitkin County
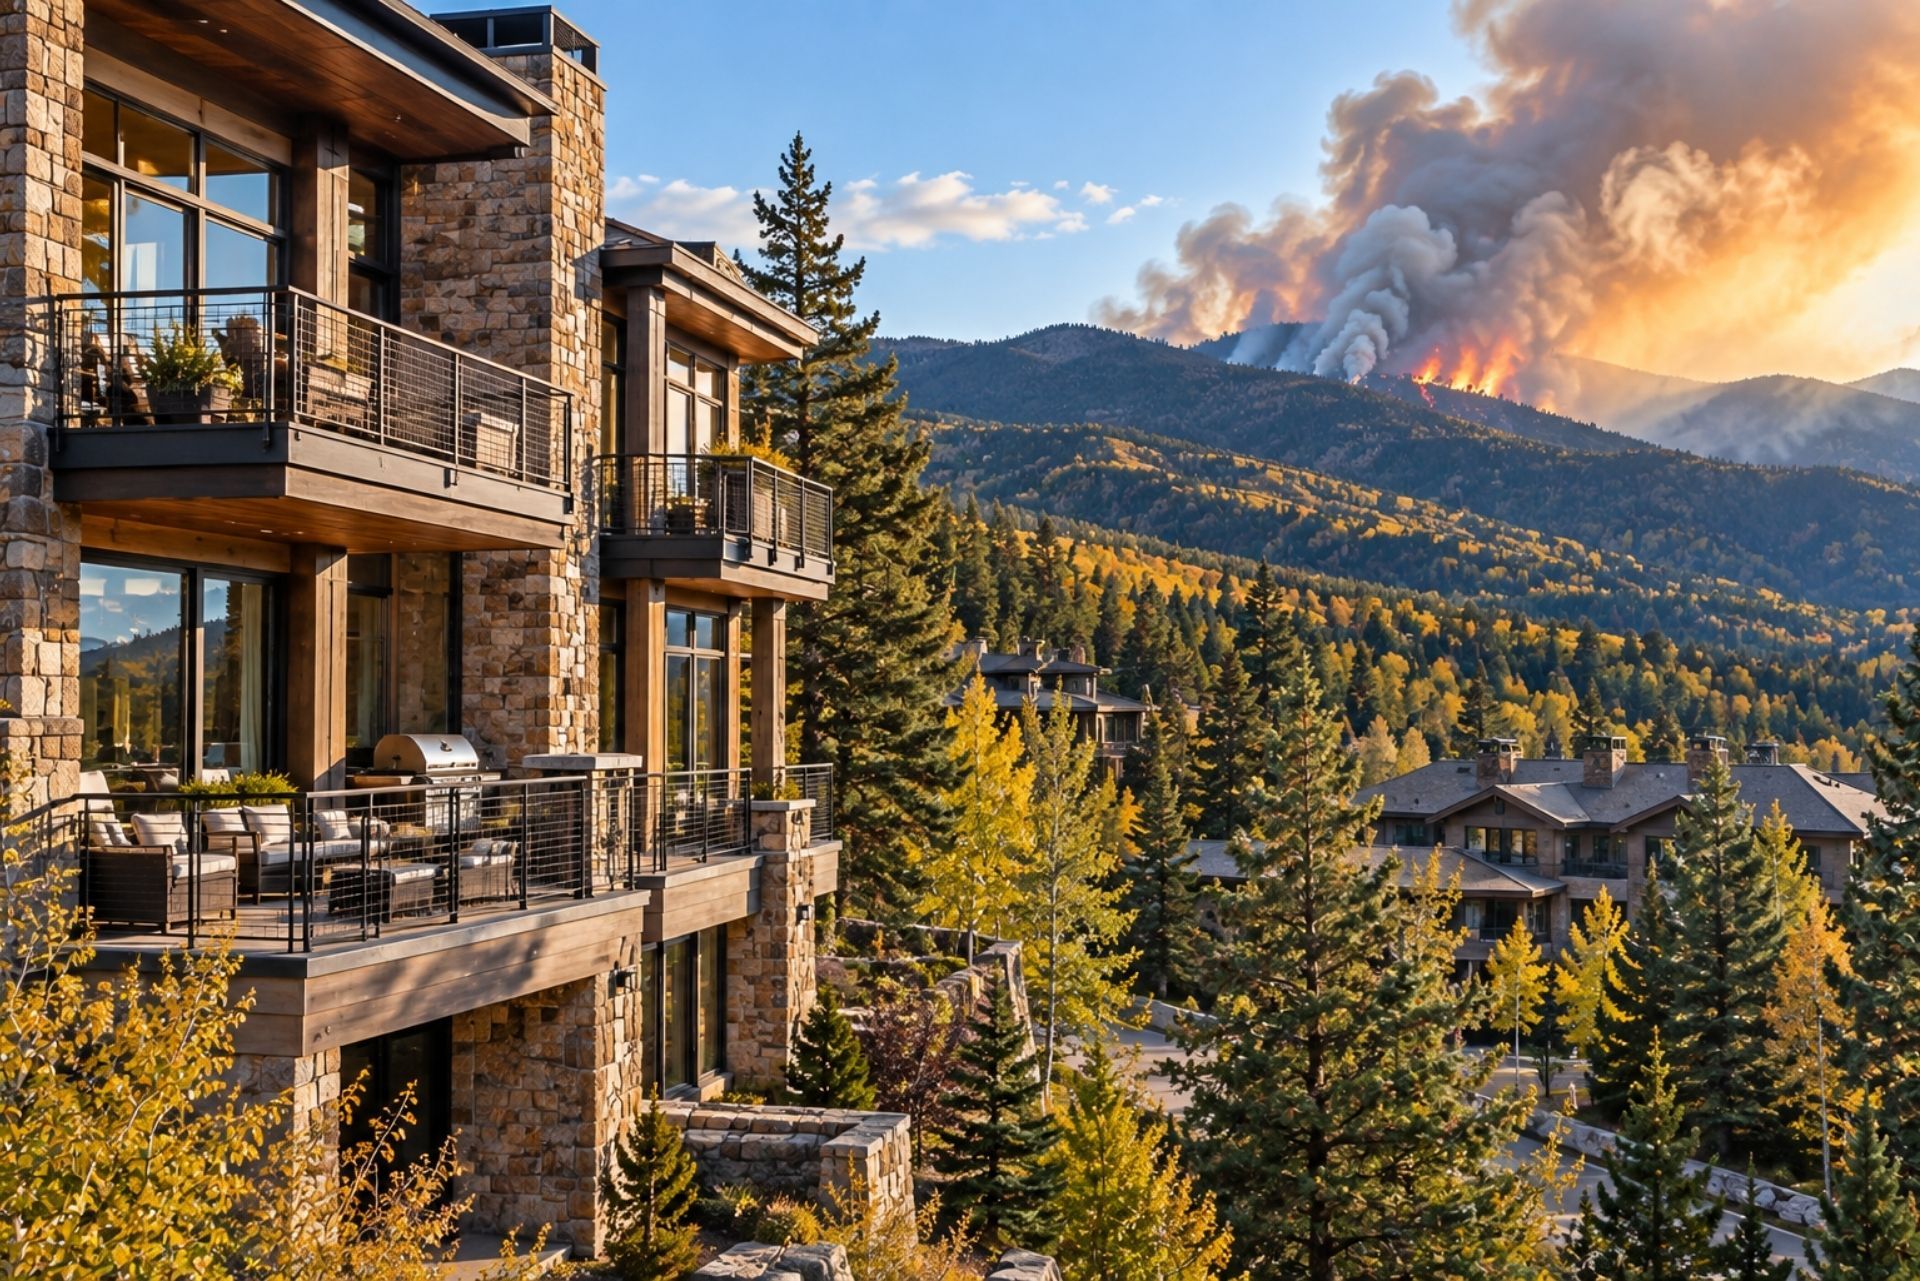
Wildfire risk isn't theoretical in the Roaring Fork Valley. The 2024 Aspen Acres Fire prompted immediate regulatory action, and Colorado's Emergency Regulation 26-E-04 now prohibits insurers from unfairly canceling or non-renewing policies for policyholders in fire-affected zones. That protection matters, but it's temporary. Associations need to focus on long-term insurability.
Understanding Fire Protection Class Ratings
Your building's ISO Fire Protection Class rating directly affects premium pricing. This rating considers proximity to a fire station, available water supply, and the local fire department's capabilities. Many Aspen-area condos fall into Class 4 or 5 territory, which is reasonable but not great. Buildings farther from town or served by volunteer departments may rate worse.
Improving your rating isn't always possible, but documenting your building's fire suppression systems, alarm monitoring, and hydrant access can help during underwriting. Carriers want to see that your building has internal defenses even if the surrounding terrain is risky.
Defensible Space and Exterior Mitigation Requirements
The Aspen Wildfire Resiliency Code, effective April 23, 2026, now requires all new building permits to include a 5-foot non-combustible "Zone 0" around all structures. This means no mulch, no vegetation, and no combustible storage within five feet of the building envelope.
Existing buildings aren't automatically subject to the new code, but associations that voluntarily comply gain a real advantage during insurance renewals. Carriers are increasingly asking for photographic documentation of defensible space, ember-resistant vents, and Class A roofing materials. Completing these upgrades before your renewal date gives your broker stronger positioning with underwriters.
Managing Liability for High-Value Properties
Liability exposure for Aspen condo associations goes well beyond the standard slip-and-fall scenario. The combination of high-net-worth residents, short-term rental activity, and amenities like pools, hot tubs, and fitness centers creates a risk profile that carriers scrutinize closely. The liability market for luxury associations remains strained due to social inflation and high-value jury awards, making adequate coverage both harder to find and more expensive.
Short-Term Rental Liability and Guest Injuries
If your association permits short-term rentals, your liability exposure multiplies. Vacation guests unfamiliar with mountain conditions slip on icy walkways, misuse hot tubs, and injure themselves on trails accessible from the property. A guest injury claim against the association can easily reach seven figures when medical costs, lost income, and pain-and-suffering damages are factored in.
Your master policy's general liability section needs to explicitly cover short-term rental activity. Some policies exclude it or sub-limit it. The association should also require individual unit owners who rent short-term to carry their own liability coverage with the association named as an additional insured.
Umbrella Policies for High-Net-Worth Owners
Individual unit owners in luxury buildings should carry personal umbrella policies well beyond their standard liability limits. Jury awards exceeding $10 million have become more common, and carriers now require higher underlying liability limits before an umbrella policy will attach.
Getting capacity for umbrella limits above $25 million is extremely tight in 2026, often requiring layered towers involving multiple surplus lines carriers. If you own a $6 million unit and rent it on a platform like Airbnb, a $1 million umbrella isn't sufficient. Work with a broker experienced in high-net-worth personal lines to structure appropriate coverage.
Coverage Comparison: Standard vs. Luxury Condo Policies
The gap between a standard condo association policy and one designed for luxury properties is significant. Here's how they typically differ:
| Coverage Feature | Standard Condo Policy | Luxury/High-Value Policy |
|---|---|---|
| Building Valuation | Replacement cost, standard materials | Agreed value, custom finishes included |
| Ordinance or Law | Standard percentage of building value | Higher or unlimited limits |
| Water Damage Sub-limit | Standard sub-limits | Higher sub-limits |
| Wildfire Deductible | Percentage-based (often 2-5%) | Negotiable with mitigation credits |
| Loss Assessment | $1,000-$2,000 per unit | Higher limits per unit |
| Business Income | 12 months | 18-24 months (critical for rental income) |
| Equipment Breakdown | Often excluded | Included for boilers, HVAC, elevators |
Standard policies leave dangerous gaps for Aspen buildings. The ordinance-or-law coverage is a prime example: if your building suffers a 50% loss and the city requires a full rebuild to current code, a 10% ordinance limit won't come close to covering the difference. Luxury policies address these gaps, but they cost more and require thorough underwriting documentation.
How Deductibles and Assessments Actually Work
Deductibles in condo insurance confuse even experienced board members. The association's master policy carries its own deductible, which can range from $10,000 to $100,000 or more depending on the peril. Wildfire deductibles are often percentage-based, which has become a dominant market feature in 2026 according to latentinsure.com. For large habitational risks like condo associations, standalone wildfire deductibles are now common, as noted by insurancebusinessmag.com.
That deductible gets passed to unit owners through special assessments. Your governing documents should specify how deductible costs are allocated, whether equally, by unit value, or by the affected unit. Without clear language in the CC&Rs, disputes over assessment allocation can become as costly as the claim itself.
Unit owners need their own HO-6 policy with a loss assessment endorsement high enough to cover their share of the master policy deductible. Most standard HO-6 policies still carry a default $1,000 to $2,000 limit for loss assessment, which is meaningless for a luxury building according to
theinsuranceloft.com.
Common Questions About Aspen Condo Insurance
What happens if our association can't find a carrier willing to write wildfire coverage? The Colorado FAIR Plan serves as an insurer of last resort, providing coverage limits up to $5 million per building for commercial properties and HOAs. It's not cheap and coverage is basic, but it prevents your association from going uninsured. Most associations use it as a bridge while improving their risk profile.
Does the association's master policy cover my personal belongings inside my unit? No. The master policy covers the building structure and common areas. Your personal property, interior improvements, and personal liability require a separate HO-6 unit owner's policy. If you've upgraded countertops, flooring, or fixtures beyond the original builder spec, make sure your HO-6 reflects those values.
Can our association be non-renewed after a wildfire claim? Colorado's emergency regulation currently prohibits unfair cancellation or non-renewal in fire-affected zones. Outside that protection window, carriers can non-renew at the policy expiration date with proper notice. Building a strong mitigation record is your best defense against non-renewal.
How often should our building's replacement cost be appraised? Every two to three years for luxury buildings. Construction costs in the Roaring Fork Valley fluctuate with labor availability and material prices. An outdated valuation creates coinsurance risk and can result in claim payments that fall far short of actual rebuilding costs.
Are hot tubs and pools a liability problem for our association? Yes. Amenities involving water, heat, and alcohol create significant injury exposure. Your policy should include specific coverage for these amenities, and your association should enforce clear safety rules, signage, and maintenance protocols.
What the 2026 Market Means for Your Renewal
The insurance market for Aspen condo associations is tighter than it was even two years ago. Carriers that once competed for luxury mountain property accounts have either pulled back or dramatically increased pricing. Wildfire losses across the western U.S. have reshaped underwriting appetites, and Aspen isn't exempt from that shift.
Associations renewing in 2026 should start the process at least 120 days before expiration. Give your broker time to approach multiple markets, including surplus lines carriers. Prepare a mitigation package that includes defensible space photos, roof material certifications, sprinkler system inspection reports, and updated appraisals. The more documentation you provide, the better your positioning.
The Role of Your Insurance Broker
Not every broker understands mountain resort property. You need someone who knows the difference between an admitted carrier and an E&S market, who has relationships with the handful of underwriters still writing Aspen luxury condo association insurance, and who can explain your deductible structure in plain language.
Ask prospective brokers how many Pitkin County associations they currently represent. Ask them which carriers they've placed wildfire-exposed properties with in the past 12 months. If they can't answer specifically, they're not the right fit.
A good broker also helps your board understand the tradeoffs between higher deductibles and lower premiums. Sometimes accepting a larger deductible makes financial sense if the association maintains adequate reserves. Other times, the risk transfer to the carrier is worth the premium.
Securing Your Investment in a Shifting Market
Insuring a luxury Aspen condo, whether you're on the association board or own an individual unit, requires more attention and expertise than most owners expect. Wildfire exposure, high replacement costs, liability from short-term rentals, and a contracting carrier market all create pressure points that standard approaches can't handle.
The associations that fare best are the ones treating insurance as a year-round risk management function, not a once-a-year renewal task. Invest in updated appraisals, complete wildfire mitigation upgrades before they're mandated, carry adequate umbrella coverage, and work with a broker who genuinely knows this market.
Your property in Aspen represents a significant financial commitment. Protecting it with the right insurance structure, from the master policy down to your individual HO-6, is one of the most practical things you can do to safeguard that investment. Start your renewal preparation early, ask hard questions, and don't settle for coverage that wasn't built for what you actually own.
ABOUT THE AUTHOR:
John Jacquat
As President of Pure Risk Advisors, I’m dedicated to helping clients protect what matters most through clear, personalized insurance solutions. Since 2009, my focus has been delivering trusted coverage and guidance for individuals and businesses across Colorado and beyond.
The Pure Risk Process
Process of Working With A Business Insurance Agent in Colorado
Risk Analysis & Tailoring
Embark on a meticulous exploration of your business's unique vulnerabilities and aspirations. Pure Risk Advisors goes beyond mere coverage, ensuring you're equipped with solutions finely tuned to Colorado’s distinct business landscape.
Strategic Business Consultation
Dive deep into a strategic session with our seasoned specialists. By delving into your business model, aspirations, and challenges, we align our insurance recommendations not just to protect but to propel your business forward, keeping in mind Colorado’s intricate regulatory environment.
Swift Policy Integration
Upon discerning the optimal protection strategy, we streamline the activation process. Partnering with Pure Risk Advisors means more than just business insurance – it's about securing your enterprise's future with unmatched diligence and expertise in Colorado.
Pure Risk Advisors Team
Meet Our Colorado Professional Team Members
Meet the heart and soul of Pure Risk Advisors: our exceptional team. Each individual has been meticulously selected not just for their deep-rooted industry knowledge, but for their passion and commitment to genuinely serve our clients.
We pride ourselves on forging more than just business transactions; we build relationships. Our team doesn't see you as just another policy number. Instead, they view every interaction as a partnership, crafting solutions that resonate with your unique needs.
Dive in, get to know us, and discover firsthand why our team makes all the difference.
Client Testimonials
Amazing Feedback About Pure Risk Advisors

In today’s insurance marketplace, innovation and originality are important - but unless they’re accompanied by integrity and personalized service, they do little to accomplish a club owner’s goals. ACE National is proud to recognize John Jacquat and his company, Pure Risk Solutions, as one of our top-ranked premier industry providers. John has consistently mastered achievement in leadership, creating the best product for a client’s needs and following through on his word. I can recommend Mr. Jacquat without reserve if you’re in the market for club insurance.
Angelina Spencer
Executive Director of Ace National
Business Insurance Coverage in Colorado
Commercial Insurance Options
Business Owner's Policy
Coverage for property damage, liability, and business interruption combined.
General Liability Insurance
Protects against business liabilities like bodily injury and property damage.
Workers' Comp. Insurance
Covers employee injury costs, ensuring business and worker protection.
Professional Liability Insurance
Guard against professional mistakes, negligence, or services rendered failures.
Commercial Property Insurance
Broad protection against business-related injuries or property damage claims.
Commercial Auto Insurance
Coverage for business vehicles against damage, injury, or liability.
We've been serving Colorado Business Since 2009
Industries Served
Latest News & Blog
Read Our Latest Articles